More Buyers Are Planning To Move in 2026. Here’s How To Get Ready.

KCM • January 16, 2026

More Buyers Are Planning To Move in 2026. Here’s How To Get Ready.


Momentum is quietly building in the
housing market. New data from NerdWallet shows more Americans are starting to think about buying a home again. Last year, 15% of respondents said they planned to buy a home in the next 12 months. This year, that number rose to 17%.

That 2% increase might not sound like a big jump, but in a market where buyer demand has been cooling for the past few years, it’s a sign things are starting to shift. More people are feeling ready (or at least closer to ready) to take the leap and buy a home in 2026.

And if you’re in that camp and buying a home is on your goal sheet this year, this is your nudge to connect with a local agent and a trusted lender to start laying the groundwork now.

Planning To Move in Early 2026? Start with These 4 Steps

If you’re eager to get the ball rolling right away, here's what to tackle first:

  1. Get pre-approved. A pre-approval gives you a real understanding of your buying power and what your payment could be at today’s rates. But keep in mind, Experian says most pre-approvals are only good for 30-90 days, so this step makes the most sense as you’re ready to get serious.
  2. Run the numbers. Look closely at all your expenses to come up with your budget. Consider what you’re spending on other bills and what your monthly mortgage payment would be once you buy. That way you go in with open eyes and you don’t stretch too far.
  3. Define your non-negotiables. Once you know the numbers work, figure out your must-haves. This includes your desired location, commute, layout, school district, lifestyle needs, etc. Getting clear on these now makes decisions easier once you start looking at homes.
  4. Choose your agent early. Look at reviews online and talk to multiple agents to find one you trust that you also click with. The right agent does more than show homes. They help you understand pricing, competition, timing, and strategy before you ever write an offer.

Thinking about Buying Later in the Year? This Is Still Your Window To Prepare

Even if buying feels like a late-2026 goal, this moment still matters. The buyers who feel the most confident later are usually the ones who quietly prepared earlier.

That doesn’t mean big financial commitments or major lifestyle changes. It just means setting yourself up so you’re ready when the timing is right. Here are a few low-stress ways to do that:

  1. Work on your credit. While you don't need to have perfect credit to buy a home, your score can have an impact on your loan terms and even your mortgage rate. So, working to bring up your score has its perks. Paying down debt now and making payments on time can help bring your score up.
  2. Automate your savings. If you have to remember to transfer money into your homebuying savings manually, you may forget to do it. So, you may want to set up automatic transfers to drive consistency and remove the temptation to spend the money elsewhere.
  3. Lean into your side hustles: Do you have a gig you do (or have done before) to net some extra cash? Taking on part-time work, freelance jobs, or picking up a side hustle can help give your savings a boost.
  4. Put any unexpected cash to good use: If you get any sudden windfalls, like a tax refund, bonus, inheritance, or cash gift from family, put it toward your house fund. You’ll thank yourself later.

The common thread here? The right prep work makes a difference.

Bottom Line

If buying a home in 2026 is on your radar, let’s start the conversation today. Not to rush a decision, but to make sure you know how to get ready for your moment.

Because every move (whether it’s next year or later) is smoother when it starts with a plan. And if you need help coming up with one that works, let’s connect.

Share this post
By The Lighter Side of Real Estate • September 1, 2026
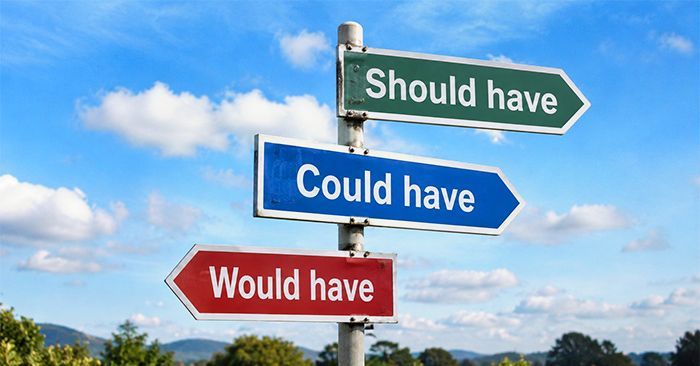
Every year, on the third Saturday of July, millions of people celebrate National Toss Away the “Could Haves” and “Should Haves” Day. OK… maybe not millions. But somebody probably does! While it’s not exactly the kind of holiday most people mark on their calendars, it’s built around an idea that’s surprisingly relatable. We all have moments we wish we could do over. Maybe you could have invested in a company before its stock took off. Maybe you should have kept that classic car instead of selling it years ago. Maybe you could have taken that job, started that business, or simply made a different decision somewhere along the way. Real estate has no shortage of “could haves” and “should haves,” either. In fact, one that’s been floating around quite a bit lately sounds something like this: “Maybe I should have sold my house a few years ago.” “Maybe I’ll just wait until the market gets better…” If you’ve been paying attention to the housing market lately, you may have noticed that some homeowners are putting their houses up for sale… and then deciding to take them back off the market. According to recent data , delistings have been on the rise as more sellers decide they’d rather wait than accept a market that isn’t quite living up to their expectations. In fact, they’re delisting at the highest rate since 2020, right around the time the pandemic began. When you think about it, it’s not hard to understand why. For several years, many sellers got used to homes selling almost immediately, multiple offers arriving within days, buyers waiving contingencies, and offers coming in above asking price. But, as real estate markets tend to do, they’ve changed in many areas. Depending on where you live, and the price range your home is in, buyers may have more choices than they’ve had in years. They may take longer to make a decision. They’re more likely to ask for inspections, repairs, seller concessions, or simply negotiate harder than they would have a few years ago. For some homeowners, that shift is frustrating enough to make them think… “Maybe I’ll just wait until the market gets better.” And for some people, that may absolutely be the right decision. Two Thoughts That Are Closer Than They Appear What’s interesting is that the two thoughts we’ve been talking about are actually pretty close cousins. “Maybe I should have sold my house a few years ago.” “Maybe I’ll just wait until the market gets better.” One is based on wishing you could go back and capitalize on yesterday’s market. The other is based on hoping you’ll recognize the right time to capitalize on tomorrow’s. They’re both completely understandable. In fact, they’re probably thoughts just about everyone has had at one point or another—not just in real estate, but in life. The catch is that neither one is particularly helpful when you’re trying to decide what to do today. After all, you can’t sell your house three years ago. And no one—not even the smartest economists—knows exactly what the housing market is going to look like three years from now. Or any other number of years for that matter. You can only make decisions based on what the market is currently doing. The Problem With Using Extraordinary as Your Baseline It’s also worth remembering that today’s market isn’t necessarily a bad market for sellers. In many parts of the country, home prices are still historically strong. In fact, if you ask many buyers how they feel about today’s market, there’s a good chance they’ll tell you homes are still too expensive and affordability remains one of their biggest challenges. What’s changed isn’t necessarily that sellers have lost all of their leverage. It’s that many of them have lost the extraordinary leverage they enjoyed just a few years ago. But now your home may take a little longer to sell. You might not have quite as many showings. Your buyer may ask for repairs or seller concessions that would have been laughed off during the frenzy of the pandemic market. None of those things necessarily mean it’s a bad time to sell. They may simply mean the market has become a little more… normal. And normal can feel disappointing when you’re comparing it to one of the strongest seller’s markets in modern history. Every Market Creates a Few “Should Haves” One of the interesting things about real estate is that every market eventually becomes the one somebody wishes they’d taken advantage of. Looking back, it’s easy to find a market where you wish you had bought, sold, or invested. The challenge, of course, is that nobody knows which market people will be saying that about until years later. Will some homeowners who decide to wait ultimately be glad they did? Absolutely. Every seller’s situation is different, and for some, waiting may prove to be exactly the right decision. But chances are, this market will also become one that at least some homeowners eventually look back on and say, “I probably should have sold then.” The only problem is that none of us knows which market that will be until we’re looking at it in the rearview mirror. That’s why “could haves” and “should haves” usually aren’t the best guide when making real estate decisions. They only show up after the fact. If you’re debating whether to sell now, wait a while, or even relist a home you recently took off the market, one of the smartest things you can do is have a conversation with a knowledgeable real estate agent. They can help you evaluate your local market, your personal situation, and your long-term goals so your decision is based on today’s realities—not yesterday’s regrets or tomorrow’s unknowns. And if nothing else, perhaps National Toss Away the “Could Haves” and “Should Haves” Day is a good reminder that yesterday’s market is gone, tomorrow’s market hasn’t arrived, and today’s market is the only one any of us actually gets to make decisions in.
By KCM • August 30, 2026
Big Investors Are Backing Off and That’s Your Opening For years, a lot of would-be homebuyers have worried about the same thing. How do you compete with big investors who can swoop in, pay cash, and snap up the houses you want? Well, worry a little less. Because right now, those big investors aren't buying up the market. They're backing out of it. Investors Are Buying Fewer Homes Than They Have in Years According to Redfin, investor home purchases just fell to their lowest level since 2020 – when the start of the pandemic temporarily caused pretty much all homebuying to pull way back. Before that, you'd have to go all the way back to 2016 to find a time when investors bought this few homes (see graph below): Why the step back? Two big reasons. First, Washington passed a housing law that takes aim at large institutional investors. To be clear, these mega investors were never as big a part of the market as the headlines made it sound. They’ve always made up a relatively small slice of housing pie. But the law still targeted the largest ones, and it worked fast. According to Thom Malone, Principal Economist at Cotality: “When Washington announced its intention to curb institutional investors’ homebuying, the market reacted. . . Cotality data shows that investment by mega investors who own 1,000 or more properties retracted almost instantly. ” Second, the housing market has cooled. Price growth has slowed in much of the country, and in some markets, prices are dipping. That makes the math a lot less appealing for investors betting on quick gains. Lance Lambert, CEO of ResiClub, explains : “Ever since rates spiked and the Pandemic Housing Boom fizzled out in spring 2022, institutional single-family rental (SFR) operators have pulled way back from buying up homes on the resale market—the math just isn't as appealing right now. Home prices and rents are no longer ripping, holding costs (property taxes and insurance) have jumped, capital markets have shifted their attention elsewhere, and elevated materials prices make renovations expensive.” They’re Not Just Buying Less – They’re Selling More This is the part most people miss. Big investors aren't just slowing down their purchases. Data from Parcl Labs and ResiClub shows the largest institutional investors are now selling more homes than they're buying – and that gap is growing these past 4 quarters (see graph below): Every one of those homes goes right back into the market for buyers like you. And since big investors tend to own homes at the lower end of the price range, a lot of what they're selling is exactly the kind of home first-time buyers are looking for. As Malone puts it : ". . . this sudden dropoff in institutional investment is a signal to first-time homebuyers that there's an opening." Less competition from deep-pocketed buyers. More homes hitting the market. And many of them at prices that work for a first purchase . That's a shift that works in your favor. Bottom Line Big investors are stepping back, and they're adding homes to the market as they go. If you've been waiting for a better shot at buying, this could be it. Let’s connect so you can see what's popping up in our area. You may have more options than you think.
By KCM • August 27, 2026
Home Price Growth Slowed Down. That May Be Changing. After more than a year of headlines talking about how home prices are going to crash , the latest data shows that price growth may be starting to pick back up again. And depending on whether you’re buying or selling, that shift means something different for you. The Numbers May Be Starting To Turn For the past couple of years, home price growth has been moderating – cooling from around 7% in mid-2024, according to Redfin (see graph below). But look at the right side of that graph. The pace of that growth appears to have hit its low point and started to turn. While a couple months of data doesn’t necessarily mean this will be a lasting trend, there are some other signs that this could continue. For example, fewer markets are seeing prices decline. According to ResiClub and Zillow, about 36% of the 300 largest housing markets had falling prices as of the middle of last year. Since the start of this year, that share has been shrinking. Now? Only 23% are experiencing those mild dips (see graph below): When fewer markets see prices falling, that means more markets are seeing prices rise again. And forecasts suggest this shift has room to run. On average, experts project home prices will rise about 2.3% nationally this year. And for that to happen, price growth would have to pick up a bit in the second half of 2026. But Remember, Real Estate Is Local While it looks like national prices may be starting to pick back up a tiny bit, that doesn’t mean that’s what’s happening in your neighborhood. National home prices are really just an average of hundreds of local markets. Some are climbing faster. Others are still cooling. But one reason the national average may be looking up is because a growing number of metros may actually be net positive for prices this year. Not long ago, the major metros were split about 50/50 – half seeing prices rise and half seeing them fall. Now, that balance looks like it’s starting to tip in a more positive direction. Just last month, more than half of the major metros saw prices go up, according to Redfin (see graph below): As Selma Hepp, Chief Economist at Cotality, explains : “. . . local markets continue to tell very different stories. Annual home price growth has changed little since the start of the year, but some markets, especially those supported by strong job and income growth in the West and more affordable Midwest markets, have seen notable acceleration in price gains.” What This Means for You Home price headlines can be confusing because they don’t always tell the full picture. Lean on an agent to understand what’s happening in your local market and what the early signs say for where prices may go from here. That’s the best way to stay one step ahead of the market. If you're buying: slower price growth has worked in your favor. You've had more room to negotiate and a budget you could plan around. If price growth is picking up in your area, buying now may mean paying less than you would later this year. If you own a home: you've been gaining equity all along, even while growth moderated. If growth keeps picking up, those gains could speed up, too. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), projects the typical homeowner will gain roughly $16,000 in housing wealth this year. And if you're thinking about selling, this shift is a good early sign for you. Just remember, the market is still pretty balanced and buyer-friendly in a lot of areas right now. Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, let's connect so you can see exactly what prices are doing in our local market and what that means for your plans. Bottom Line Home price growth slowed way down, and now it's showing early signs of picking back up. Whether you're buying or selling, let's connect so you can see exactly what prices are doing in our local market and what that means for your plans.
Show More